 中文
Ghana’s Manufacturers Just Admitted an Import Ban Would Fail. That’s Progress.
There is a sentence in Ghana’s current leather debate that deserves more attention than the surrounding rhetoric, because it is the kind of admission industry bodies rarely make in public: the country is not ready to ban imported footwear.
The statement came from Tonyi Senayah, chief executive officer of footwear manufacturer Horseman, in the context of an industry-wide call for support. He identified raw material supply and production capacity as major challenges for local footwear manufacturers, and said plainly that Ghana could not yet ban imported footwear because domestic manufacturers could not meet local demand.
That is not defeatism. It is the most useful thing anyone has said about Ghanaian footwear policy in years.
What the industry is actually asking for
The Association of Ghana Industries (AGI) has put forward a case built on three constraints. Edwina Assan, chairperson of the AGI’s Garment, Textile and Leather Sector, said local manufacturers have the ability to produce quality leather products but need better access to buyers and new business opportunities. She added that stronger collaboration among industry players and other stakeholders could help manufacturers reach new markets, and noted that local companies already produce leather goods including footwear for Ghana’s security services — but limited awareness restricts their market reach.
That last point is revealing. Ghana’s manufacturers already supply uniform and security footwear, which means they have demonstrated basic capability in durability, sizing consistency and repeat production. What they lack is visibility with commercial buyers.
Senayah’s contribution filled in the production side: raw material supply and production capacity as the binding constraints, plus a call for investment in skills development, stronger business structures and better market access. He also suggested sourcing leather from other African countries with stronger production capacity to improve availability and potentially reduce costs.
The raw material paradox
Senayah’s cross-border sourcing suggestion is the most commercially interesting idea on the table, and it deserves to be taken seriously rather than treated as an admission of weakness.
Ghana has a substantial livestock sector but an underdeveloped tanning base. The country’s leather availability is constrained by the same factors that limit it across West Africa: hide quality, collection infrastructure, curing capacity and the diversion of hides into informal regional trade. Nigerian hides move to West Africa’s food markets; Ghanaian hides face their own leakage into unprocessed export.
For a footwear manufacturer, leather is typically the single largest material cost line, often 40-60% of the bill of materials for a leather shoe. If domestic leather is expensive, inconsistent in grade, or unavailable in the widths and thicknesses a production run requires, no amount of tariff protection makes the factory competitive. Importing semi-processed or finished leather from Ethiopia, Kenya, South Africa or Egypt — origins with more developed tanning capacity — can be a rational input strategy while local tanning develops.
That is precisely what the industry’s separate demand for lower import duties on raw materials addresses. The Ghana Leather and Footwear Manufacturers Association has called for lower import duties on raw materials and stricter checks on finished synthetic products entering the country, particularly from China. Read together, the two positions form a coherent policy: make inputs cheaper, make finished imports comply with rules, and do not pretend domestic supply exists before it does.
Why the import ban admission matters
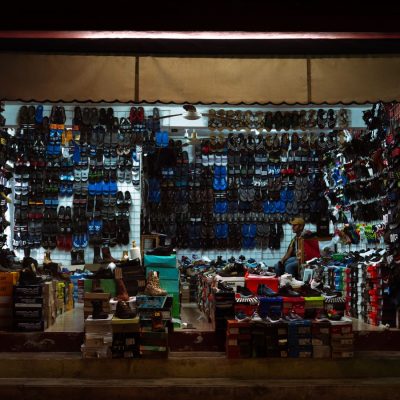
Import bans are politically attractive and economically treacherous in equal measure. When a country restricts footwear imports faster than domestic capacity grows, three things typically happen: prices rise for consumers, quality falls, and informal cross-border inflows expand to fill the gap — undercutting the very manufacturers the ban was meant to protect, while removing their activity from the tax base.
Ghana’s leather and footwear sector is not yet at a scale where it could absorb national demand. Senayah’s assessment that manufacturers cannot meet local demand is correct, and it is the reason an abrupt ban would backfire. Acknowledging that openly gives policymakers room to sequence properly: build capacity first, protect selectively later.
What would actually move the needle
Three interventions are worth more than tariff protection at this stage.
First, buyer access. AGI’s emphasis on market access is well placed. Ghanaian manufacturers need to be in front of institutional buyers — uniform services, schools, hospitals, hospitality groups — and export buyers in ECOWAS markets. Trade missions and buyer-supplier matchmaking are cheap and underused.
Second, leather sourcing strategy. A regional procurement arrangement, whether formal or through commercial intermediaries, could resolve the input constraint faster than building a tannery. This is the same logic Eswatini is now exploring through a joint procurement framework for its artisans and SMEs.
Third, professionalise business structures. Senayah’s call for stronger business structures points at a real weakness: many West African footwear producers operate informally, which blocks them from bank credit, export documentation and large tenders. Formalisation is unglamorous and decisive.
Ghana’s industry has correctly diagnosed its own position: capable, under-visible and constrained at the input end. The temptation will be to demand protection. The smarter play — and the one the industry itself is signalling — is to fix leather supply, win institutional orders and grow into the market it cannot yet serve.
Source: Leather News (leathernews.org)